
The market is fixated on when Big Tech will generate economic value from the $650 billion+ being poured into AI data center expansion annually. The market is missing the point. Monetization has never been Big Tech’s weakness as explosive revenue growth and high margins have defined their businesses for decades. While execution risk always exists, these companies remain the world’s most reliable operators at scale.
Instead, the real risk to the AI economy lies in the physical constraints of scaling these AI ambitions — not in compute availability from companies like Nvidia or Broadcom, and certainly not in Big Tech’s software capabilities, but in power availability, thermal management, and infrastructure that were never designed for this magnitude of demand.
Nvidia’s GPU road map is bringing about an immediate need to overhaul data centers as most data centers today are incapable of powering the kilowatts required for rack-scale systems. Blackwell power requirements of 120 kW for the GB200s and 140 kW for the GB300s represents a 2X increase from the H200s 70kWs. As we look out over the next 1-2 years, it’s expected Nvidia will ship rack-scale systems requiring 300-600 kW – or a 5X increase from what was needed per system in the first half of 2025.
Therefore, it is not enough to say the AI economy needs more power, but rather it needs power urgently. These are two entirely different matters; for example, the first could be supported by the expansion of nuclear power and the electrical grid, but the latter cannot. In fact, combining these two is something very few companies can do.
This leads me to my Top Pick for 2026 – Bloom Energy.
Bloom Energy offers onsite power generation through solid oxide fuel cells that are behind the meter to reduce dependency on the grid. By providing behind-the-meter generation, Bloom reduces reliance on utility infrastructure and accelerates time-to-power for customers. An added benefit is the United States is the largest producer of natural gas, therefore, Bloom does not struggle to secure supply given the United States has large, well-developed gas supplies and pipeline infrastructure.
The I/O Fund’s History on Bloom Energy
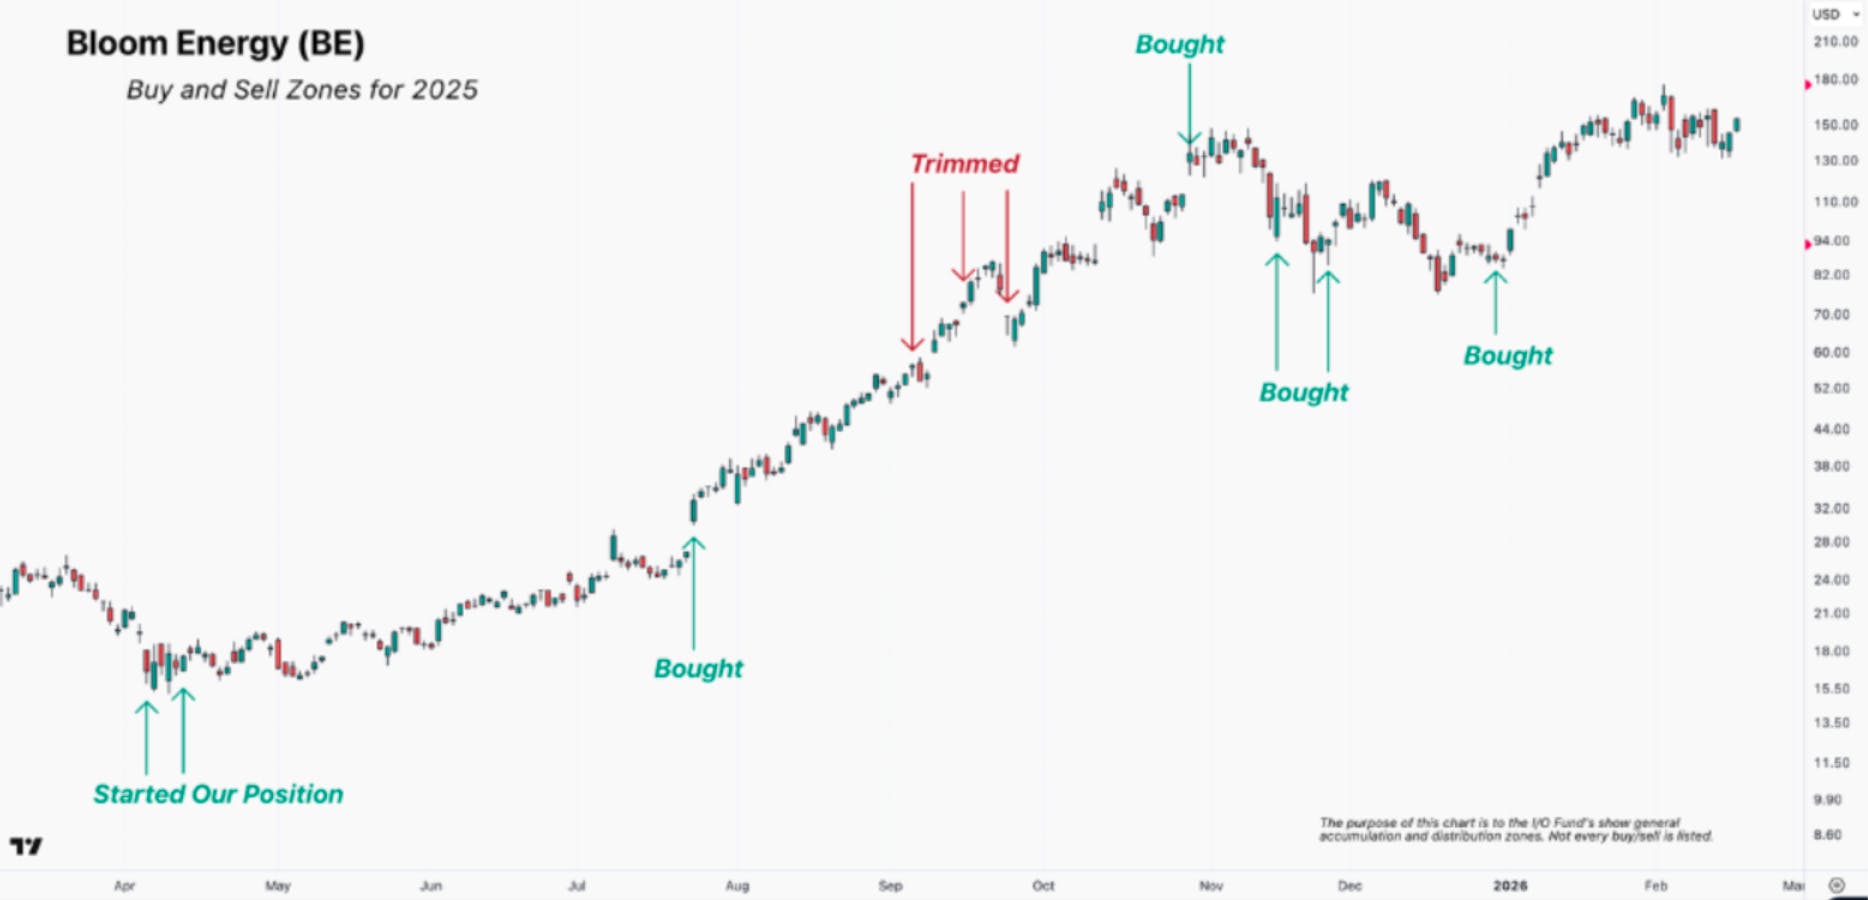
We first covered the surging power demand from AI data centers in our June 2024 newsletter, AI Power Consumption: Rapidly Becoming Mission-Critical, with Bloom Energy quickly rising to the top of our list for its ability to solve the critical time-to-power constraint. From there, we drilled deep into this stock in early 2025 yet used technical analysis to hold off and wait for the April lows for our first entries.
We made our initial buys at $16.64 and $17.04 in April 2025, helping position the stock as our biggest winner of 2025. During 2025, we held the position at allocations as high as 15%, with real-time trade alerts sent to our Members throughout the year. Today, the stock trades at $160.90, while many of Wall Street’s most renowned firms followed later in 2025 and entered at significantly higher prices.
With that said, it requires strong conviction in not only Bloom Energy’s positioning but also the sheer pressure from AI’s primary bottleneck to believe the stock could see a repeat year of strong performance. Below, I lay out why I believe Bloom Energy is setting up to do exactly that.
Power is the #1 Constraint for AI Data Centers
Before we drill deeper into Bloom Energy’s unique positioning, it’s well worth the time to revisit the mounting pressure in the AI energy bottleneck. Consider that companies like Microsoft and Meta are spending hundreds of billions annually on AI, with tens of billions allocated to Nvidia’s Blackwell GPUs.
Any delay in powering these systems deepens both risk and market perception, as it not only pushes out revenue and profits but also extends the period in which Big Tech remains underwater on capex returns. A long timeline for power availability increases both timing risk and financial leverage.
Competitively speaking, power availability is also an advantage as providers that can energize and deploy GPUs faster will have a meaningful head start over competitors stalled by power constraints. While the concept is straightforward, the stakes are immense, as it is not only the scale of these AI investments to consider but also the fierce competition to secure power can amplify the consequences of a delay.
AI leaders are in unison this is the predominant challenge the industry faces. Commentary from executives at hyperscalers, neoclouds, Bitcoin miners, colocation providers and commercial real estate firms all point to power as a key constraint (and consideration) facing the market this year and next.
CBRE said in its H1 2025 North America Data Center Trends Report that “power availability and infrastructure delivery timelines remained the most decisive factors shaping site selection, leasing activity and pricing across all major U.S. markets.”
Equinix executives stated that “the amount of power we need isn’t sitting around on the grid. And so we are planning, and I think most people in the room that are doing data center development are ensuring you have clear line of sight to that power before you take down any land or plan any data center capacity.”
A survey by Bloom Energy of 44 hyperscaler and colocation developers found that availability of power was the number one consideration for new site selection, with 84% of respondents placing that in the top 3 with an average rating of 7.8 out of 10.
Amazon CEO Andy Jassy said that “you see some of the constraints and they kind of exist in multiple places, [but] the single biggest constraint is power.” Microsoft CEO Satya Nadella said Microsoft needs “power in specific places so that we can either lease or build at the pace at which we want.”
Google Cloud’s Thomas Kurian explained that “more powerful chips… take a lot more power. And power is, in many cases, a short resource.” Arm’s CEO Rene Haas has said that without improvements in efficiency, “by the end of the decade, AI data centers could consume… 20% to 25% of U.S. power requirements. Today that’s probably 4% or less.”
AI Data Center Power Demand Forecast for 2030: Projected to Surge 8,050%
Data center power demand is expected to grow at an accelerated clip through the end of the decade and beyond, driven by the two main drivers of more powerful GPUs and surging growth in inference.
In 2024, we had revealed that “Wells Fargo is projecting AI power demand to surge 550% by 2026, from 8 TWh in 2024 to 52 TWh, before rising another 1,150% to 652 TWh by 2030. This is a remarkable 8,050% growth from their 2024 projected level. AI training is expected to drive the bulk of this demand, at 40 TWh in 2026 and 402 TWh by 2030, with inference’s power demand accelerating at the end of the decade.”AI power demand to surge 550% by 2026, from 8 TWh in 2024 to 52 TWh, before rising another 1,150% to 652 TWh by 2030. This is a remarkable 8,050% growth from their 2024 projected level. AI training is expected to drive the bulk of this demand, at 40 TWh in 2026 and 402 TWh by 2030, with inference’s power demand accelerating at the end of the decade.”
However, we have more data from the IEA that projects global data center power demand to more than double from ~415 TWh in 2024 to ~945 TWh by 2030 under its base-case scenario, or growth of roughly 530 TWh. The agency’s AI ‘lift-off’ scenario projects demand reaching 1,250 TWh, or growth of ~835 TWh, more closely aligning with Wells Fargo’s projection.
Regardless of where AI demand falls relative to these projections, the trend and takeaway is rather clear – AI is set to drive data center power demand much higher by 2030. We can also look at this from a GW perspective, with numerous projections all pointing to substantial growth in data center capacity.
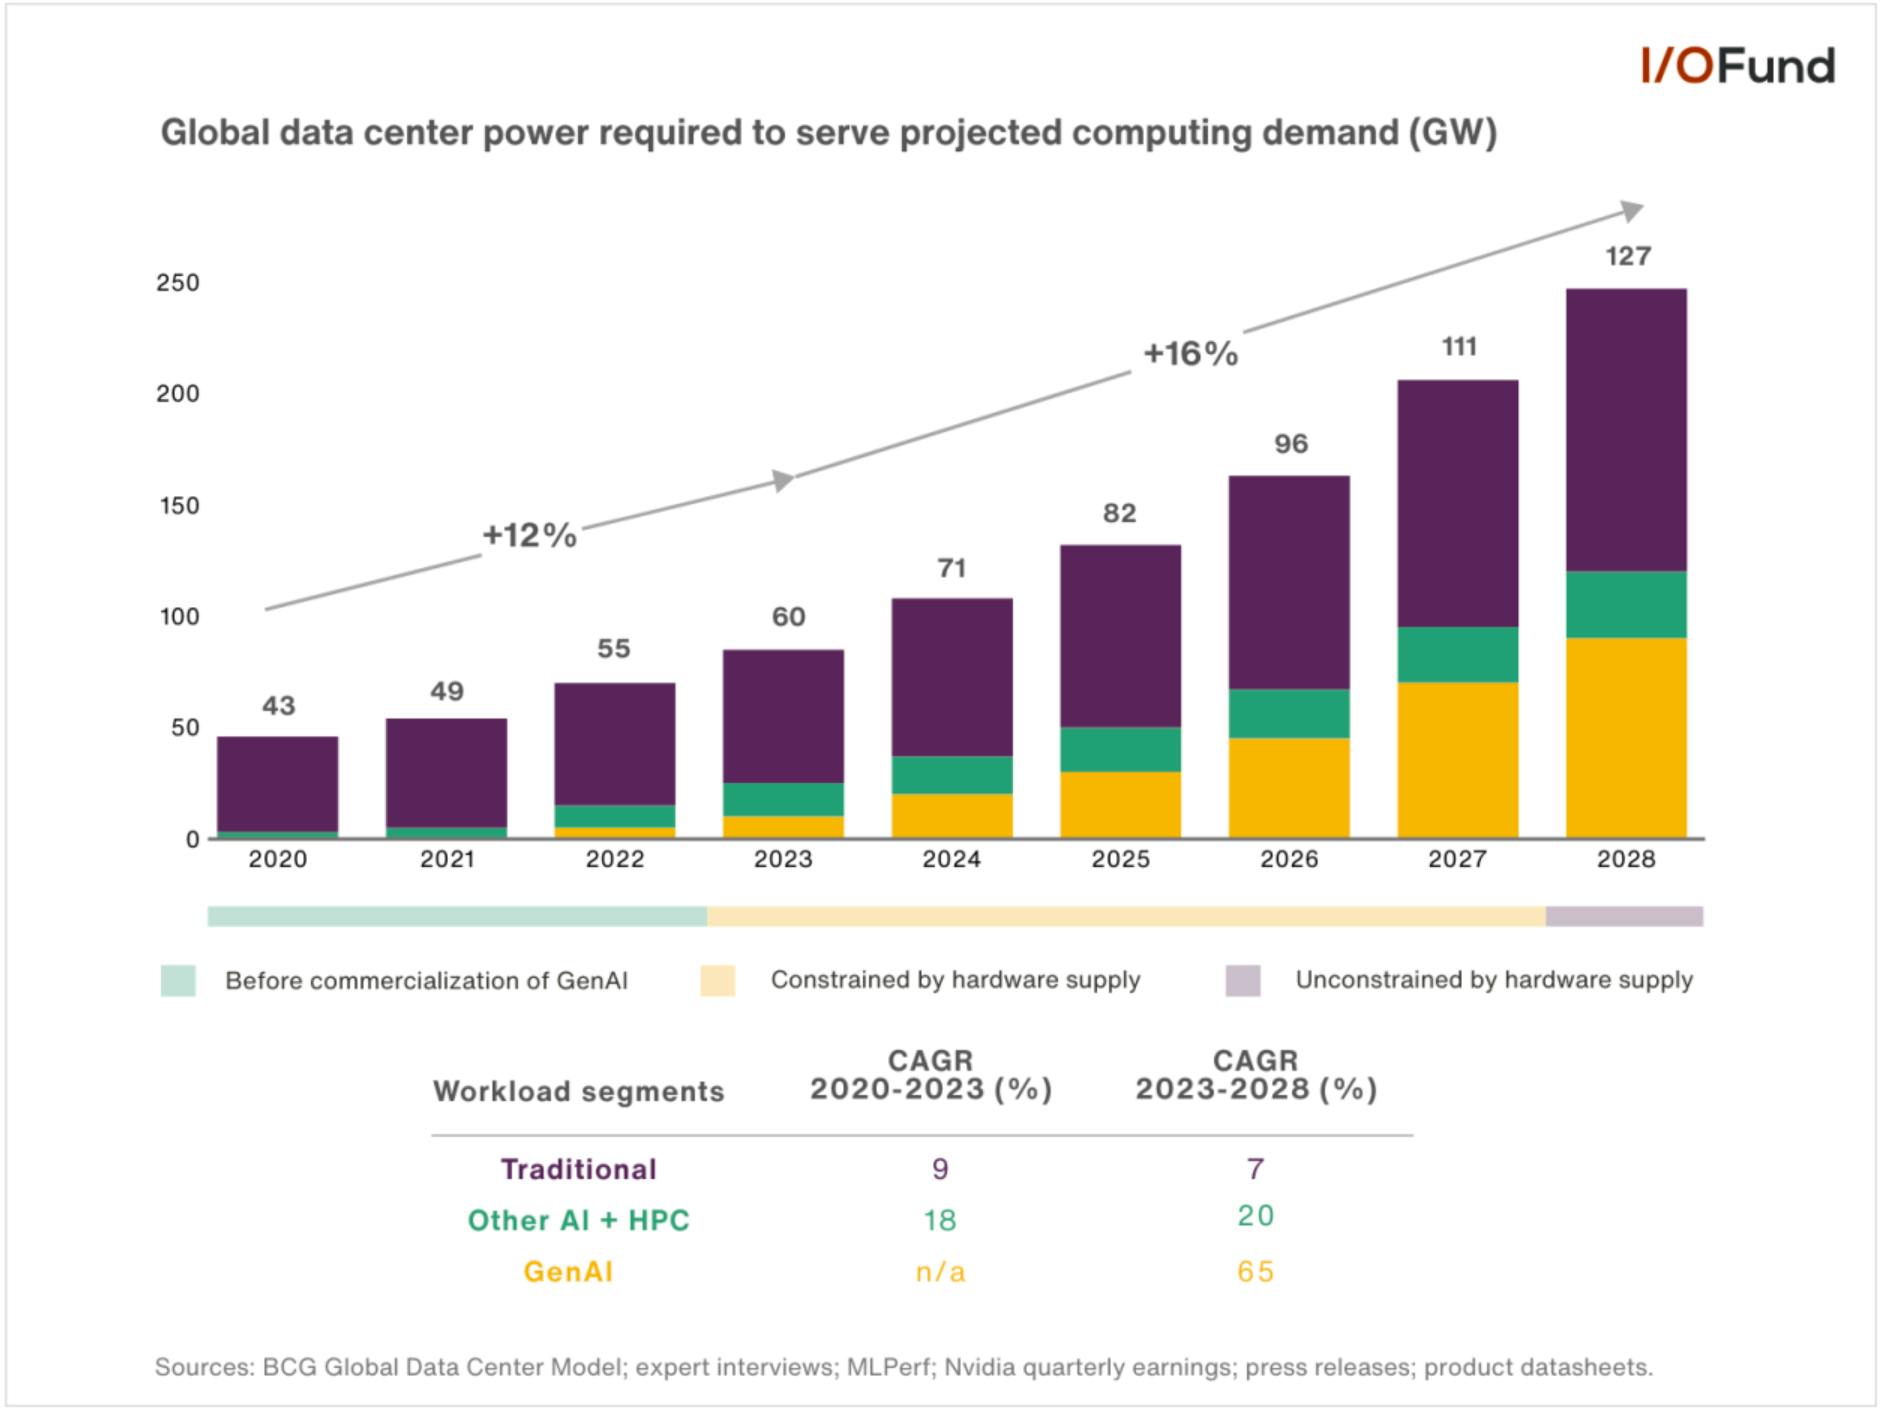
Boston Consulting Group forecasts 45 GW of growth in global data center power demand in just three years from 82 GW in 2025 to 127 GW by 2028, with this more than doubling from 2023’s 60 GW.
Overall, BCG expects generative AI power demand to rise at a 65% CAGR from 2023 through 2028, with AI training increasing at a 30% CAGR and inference rising at a rapid 122% CAGR. Under BCG’s scenario, gen AI will account for more than one-third of global data center power demand by 2028.
On the other hand, McKinsey projects data center capacity will rise ~2.5x to 219 GW by 2030, up from a similar ~82 GW baseline in 2025. McKinsey projects AI training and inference demand to rise at a nearly 29% CAGR by 2030, driven by inference, rising at a 35% CAGR from ~21GW to ~91GW. In total, AI would be contributing ~112 GW of the projected total 137 GW demand growth.
This is quite a substantial amount of projected capacity growth over the next three to five years. But, more importantly, what level of capex does this require?
Given our prior calculations for each GW to cost between $30 to $38 billion from the ground up (and now towards >$40 billion with Nvidia’s Blackwell Ultra), building out 112 GW of AI training and inference capacity by 2030 could necessitate as much as $4.3 trillion in capex.
Looking more directly at the power side, and more specifically what Bloom’s TAM could be in the realm of on-site generators, Bernstein analysts estimate that generators and turbines could account for ~6% of capex per GW. This would equate to roughly $1.8 to $2.4 billion per GW, or in the long-term scenarios noted above with 112 GW of growth tied to AI, as much as $258 billion. BofA takes a more conservative approach at roughly ~2% of capex per GW, or ~$800 million, placing this 112GW forecast opportunity at nearly $90 billion.
Why Bloom Energy Stands Out in a Crowded Energy Industry
Time-To-Power Solutions for AI Infrastructure
Our primary message has been “time to power” for Bloom, and the company continues to stand out for this very reason as it is finding strong product market fit in AI data center power needs. This is a key advantage as on-site power is becoming more of a necessity as grid constraints and connection timelines rise.
As we had noted above, the industry is expecting to see significant demand growth over the next few years, yet the primary hurdle is that the grid is not able to keep up with such rapid demand in a short timeframe. For example, PJM (home to Data Center Alley in Northern Virginia as well as fast-growing data center markets in Pennsylvania and Ohio) fell short of its reliability requirements in the last two capacity auctions, with the most recent 2027/28 planning year, falling ~6.6GW short.
A similar dynamic is unfolding in Texas, where ERCOT’s interconnection queue has reached roughly 226 GW as of mid-November, nearly quadruple the 63 GW recorded at the end of 2024. Of that total, approximately 165 GW comes from data center projects targeting approval by 2030, whereas ERCOT added only 23 GW of new capacity in 2024–25 — about 10% of the queued demand.
This further validates Bloom’s positioning by enabling new data center projects to come online sooner with on-site, behind the meter power without sitting in interconnection queues for years at a time. Bloom has already proven that it can quickly establish data center power solutions in a rapid manner, completing shipments to Oracle Cloud Infrastructure in just 55 days of its 90-day delivery request.
Its fuel cells are also fuel-flexible and can run on natural gas, biogas, or hydrogen, and provide continuous power with 99.9-99.999% reliability metrics. They are also modular in nature and can scale from 20 MW to 500 MW+, allowing flexibility in deployments and ease of scaling. Bloom is also continuously improving on price-performance, stating that its fuel cells have seen double digit YoY cost reductions each year for the past ten years, and a 10X increase in power production in the same footprint versus ten years ago.
Bloom Energy vs. Gas Turbines for Data Centers
Bloom also has an advantage over gas turbines when it comes to on-site power demand, as GE Vernova had stated in December that its gas turbines are sold out through 2028 with less than 10% remaining in 2029, meaning any new orders would not be delivered for another 3+ years. Nuclear has been floated as a solution to meet GWs of demand, though restarting facilities take years and SMRs are not expected to be commercially viable at scale until the 2030s.
From Oracle to Quanta: Bloom’s Rapid AI Power Deployment
Doubling capacity this year to 2GW gives Bloom an outlet to meet immediate-term demand from data centers throughout this year into 2027.
A subsidiary of American Electric Power (AEP) had entered into a deal with Bloom in November 2024 for the purchase of 100MW of solid oxide fuel cells with the option to purchase 900MW more, for a total of 1GW.