
This article was originally published on Forbes on Updated Oct 24, 2024, 09:01pm EDTForbesForbes on Updated Oct 24, 2024, 09:01pm EDT
Tesla is arguably one of the most advanced AI companies in the world, yet its stock is dictated by margins. Over the past three years, Tesla’s average gross profit per vehicle has declined by 60%, falling from more than $14,400 in Q3 2021 to less than $6,000 in Q2 2024, highlighting the difficulty Tesla has faced in a high-interest rate environment.
Higher interest rates have forced Tesla to place more emphasis on affordability, either via price cuts or promotional financing rates, pushing average selling prices lower and thus impacting margins. Q3’s report showed that margins may have bottomed, despite weakness in vehicle selling prices due to that focus on affordability.
Perhaps the long-term story is recurring software revenue from robotaxis and humanoid robotics, however, margins are driving the stock price for now.
Below, I look at the puts and takes of an AI front runner that is battling economic headwinds.
Deliveries Recover, But Revenue Doesn’t
Q3 saw Tesla report sequential growth for both production and deliveries after a weak Q1, where deliveries dropped below 400,000 for the first time since late 2022. Tesla reported deliveries of 462,890 EVs in the third quarter, a 6.4% increase from last year and a 4.3% increase from the second quarter.
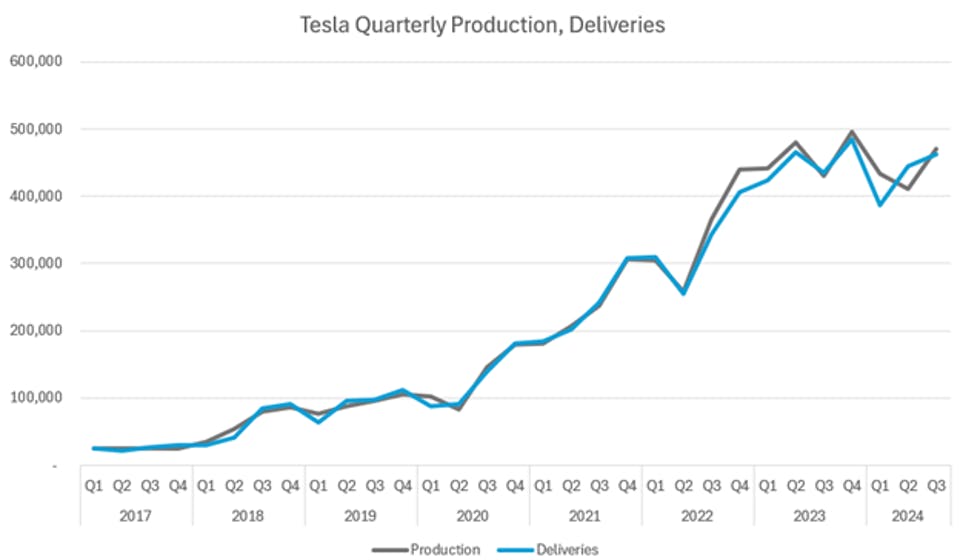
Tesla reported deliveries of 462,890 EVs in the third quarter, a 6.4% increase from last year and a 4.3% increase from the second quarter.
Source: Tech Insider Network
For the third quarter, Tesla reported automotive revenue of $18.83 billion, up just 1.3% YoY and 1.6% QoQ, and short of the consensus estimate for $19.50 billion. As a result, Tesla’s overall revenue fell short of estimates, with Tesla reporting $25.18 billion in revenue, nearly half a billion below the consensus for $25.67 billion.
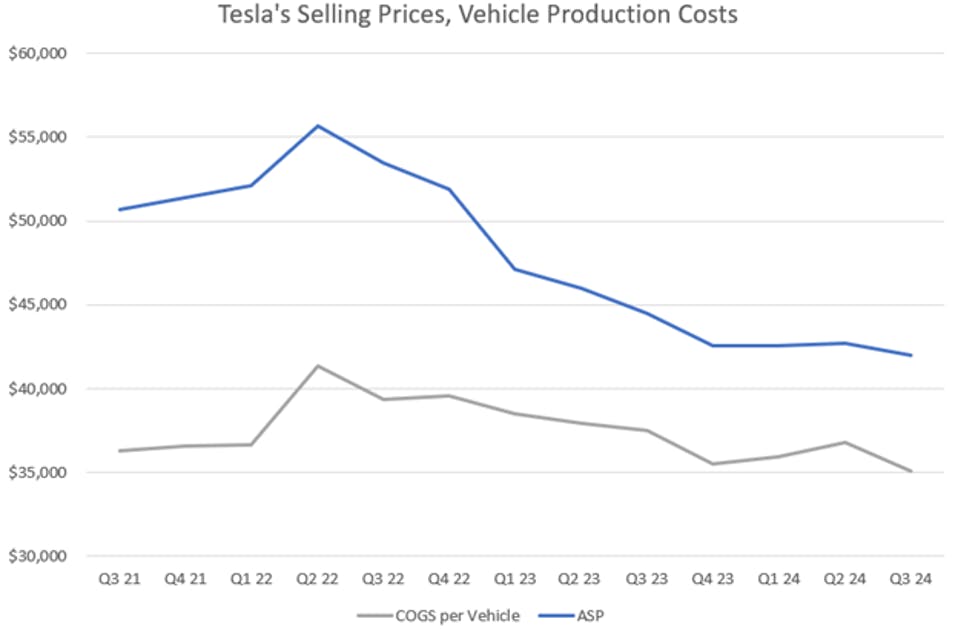
A quick look at the growth rates shows that automotive revenue growth lagged delivery growth by just over 5 percentage points, at 1.3% versus 6.4%. This tells investors that automotive selling prices declined once again, and to a large degree – Q3’s ASP fell below $42,000, down ~(1.7%) from Q2 and falling (5.6%) from nearly $44,500 last year.
Notably, there is risk the ASPs fall lower in Q4 as Tesla continues to cut some prices, with the Cybertruck seeing up to 20% cuts on different model variants in October. Musk mentioned that Tesla would be aiming for YoY growth, and with just Q4 left, that means Tesla would have to deliver more than 515,000 vehicles, a record high. This would also imply an acceleration to 11% QoQ growth, leaving the door open for more aggressive price cuts to spur demand, something management hinted at in the earnings call.
Tesla is aiming high for 2025, with Musk stating that the automaker is shooting for “20% to 30% vehicle growth next year,” or roughly at least 2.1 million vehicles assuming Tesla ends 2024 at around 1.75 million. Taneja added that Tesla’s “focus remains on growing unit volume, while avoiding a build-up of inventory. To support this strategy, we're continuing to offer extremely compelling vehicle financing options in every market.”
The Fed has forced Tesla to focus on financing and affordability, which in turn, has been a major driver of margin issues. I noted in July 2023 that the “comment on interest rates is the most important comment from the call as high interest rates mean Tesla must lower prices,” and that Tesla was “one of many tech stocks whose revenue growth and profitability is on borrowed time until the Fed instills a more dovish policy.”
Sign up for I/O Fund's free newsletter with gains of up to 2600% because of Nvidia's epic run - Click hereClick hereClick here
Tesla’s Profitability Improved on Cost Optimizations
Despite ASPs declining again sequentially, profitability improved and automotive margins recovered as Tesla captured some tailwinds from “lower raw material costs, freight and duties” and drove vehicle production costs to a record low.
Tesla headed into Q3’s report facing a tough test, as average selling prices were flat and vehicle production costs were rising. From Q4 2023 to Q2 2024, ASPs were relatively unchanged while production costs rose 3.7%, denting both automotive margins and impacting profitability. This had been hindering Tesla’s ability to revitalize automotive gross margins — as a result of those two changes, automotive gross margins took quite a large hit, falling from 17.2% to 14.6% in that two-quarter span.
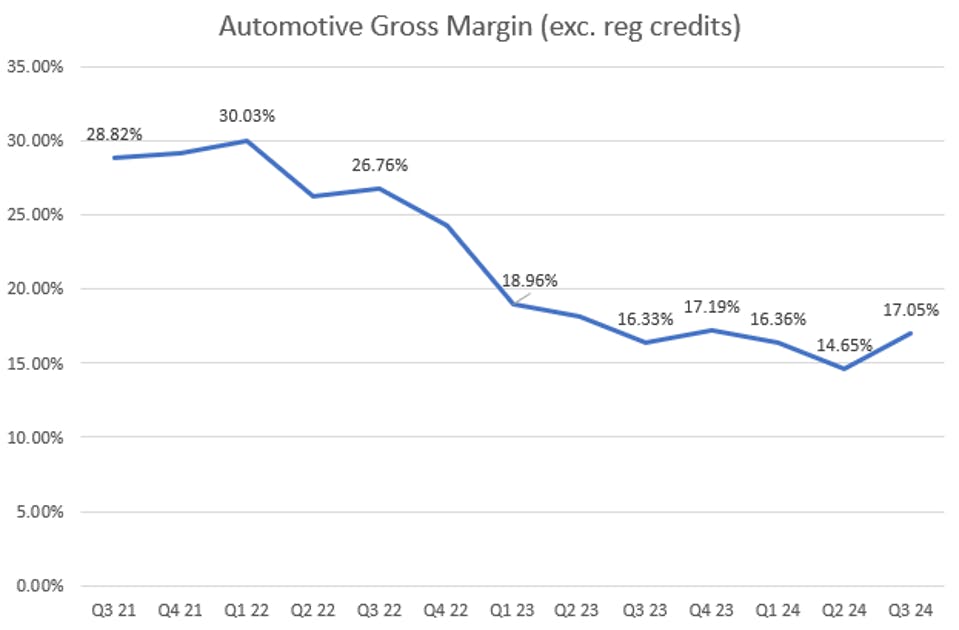
Q3 saw a sharp improvement in automotive gross margin, expanding ~240 bp QoQ and ~72 bp YoY, as Tesla drove production costs to a record low of ~$35,106.
Source: I/O Fund
Q3 saw a sharp improvement in automotive gross margin, expanding ~240 bp QoQ and ~72 bp YoY, as Tesla drove production costs to a record low of ~$35,106, dropping ~(4.6%) from $36,802 just last quarter.
Because of the large improvements in production costs, average gross profit per vehicle bounced back, increasing ~16.3% QoQ to reach ~$6,886, up from $5,921 last quarter. Essentially, Tesla manufactured and sold 14,000 more vehicles this quarter for ~$220 million cheaper than last quarter.
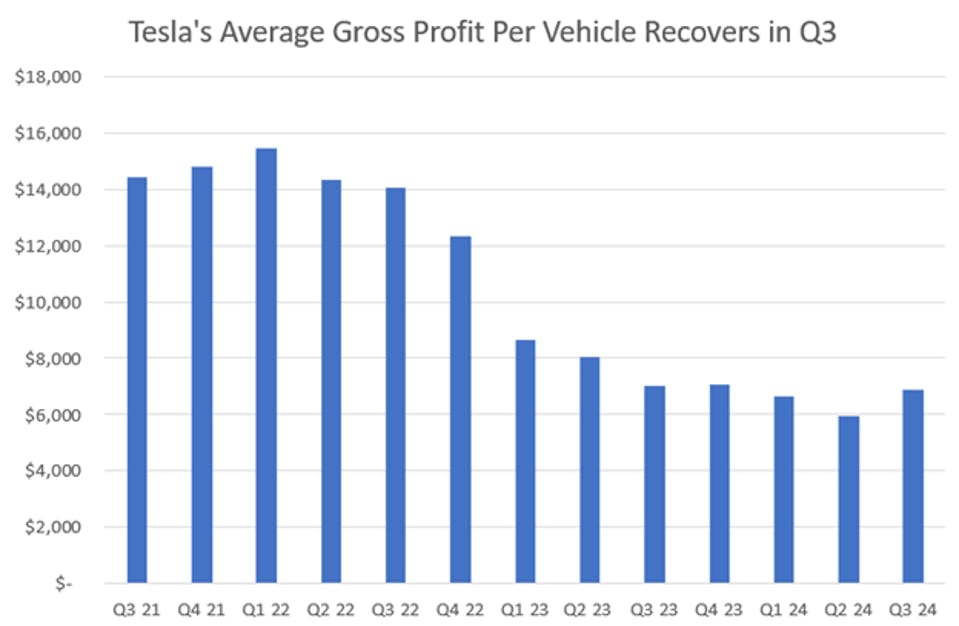
Average gross profit per vehicle bounced back, increasing ~16.3% QoQ to reach ~$6,886, up from $5,921 last quarter.
Source: I/O Fund
Operating margin also rebounded significantly, expanding to 10.8% in Q3, up from 6.3% in Q2 and 5.5% in Q1. This newfound operating margin growth adds more confidence in the margin recovery story, which has been paramount for investors as share price declines have correlated quite closely with operating margin contraction.
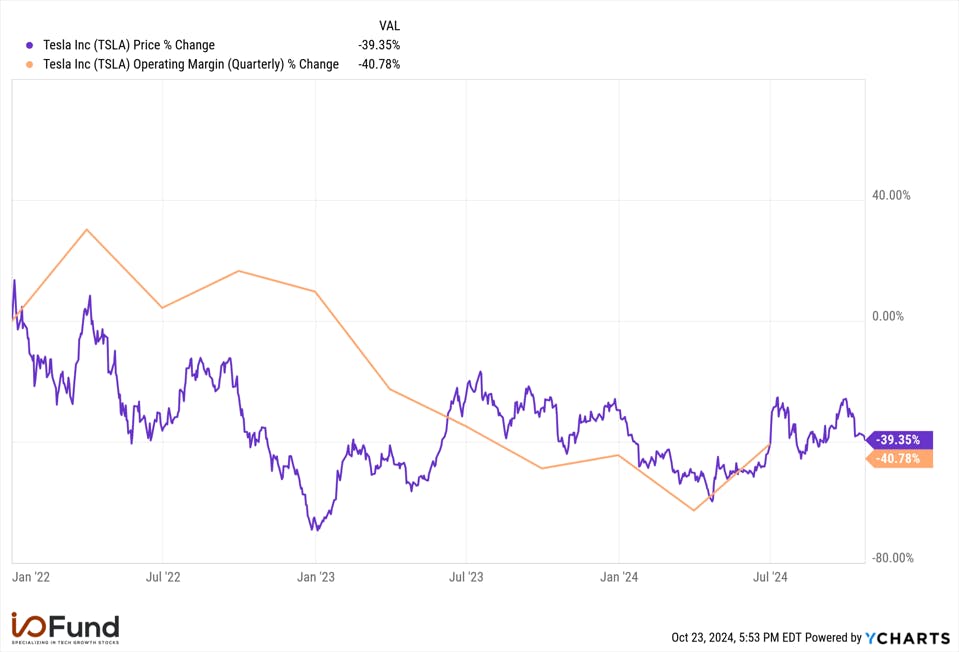
Tesla's share price declines since late 2021 have correlated quite closely with operating margin contraction.
Source: YCharts