
This article was originally published on Forbes on Jan 1, 2025,06:21pm ESTForbes Forbes on Jan 1, 2025,06:21pm EST
The Nasdaq 100 is capping off 2024 with a return of 27.0%, building upon 2023’s 53.8% return (its best year since 1999). Since the start of 2023, the Nasdaq 100 has nearly doubled with stellar returns of 95.3%, its second highest two year performance since 1998 and 1999’s 274.2% rise.
This year, the Nasdaq had countless winners and strong repeat performances from AI leaders like Nvidia, but 5 stocks took the market by surprise with significant outperformance relative to the broader indices. I think it’s important to pause and draw some parallels around the stocks that performed well in 2024 to form an opinion on what might perform well in 2025, as many of the year’s top performers shared similar fundamental improvements or had similar thematic tailwinds such as AI, nuclear and quantum computing.
Below, I review five of the top stocks of 2024, selected based on their price action, fundamentals and presence withing leading tech themes. Choosing a top 5 means many great stocks were left off this list, yet this sample helps to form conclusions around how 2024 shaped up versus years past, centered around leading, core thematic opportunities.
Read about our Top 5 Stocks from 2023 here and our Top 5 Stocks from 2022 here – many of which went on to lead the following years.here and our Top 5 Stocks from 2022 here – many of which went on to lead the following years.
AppLovin (APP)
AppLovin was one of the Nasdaq’s best performers, up 735%and joining the Nasdaq 100 on a special rebalance in November. From the start of 2024, AppLovin rose from a mere $13 billion valuation to $111 billion, peaking above $135 billion in early December – the stock has done the unthinkable this year, awakening a low-growth mobile gaming ads industry with an AI engine that is showing demonstrable results.
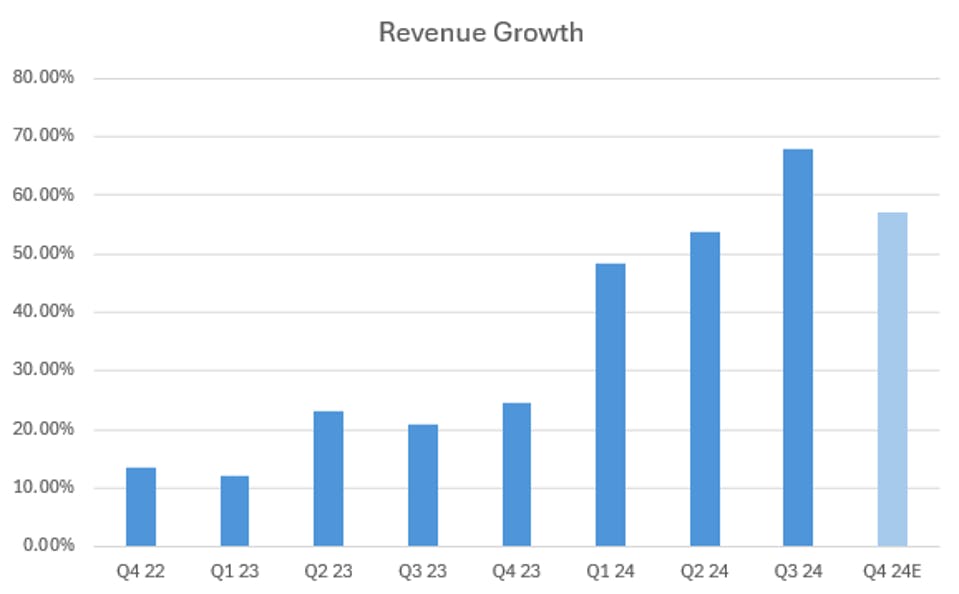
This meteoric rise stems from APP’s AXON 2.0 AI advertising engine, which has driven significant revenue acceleration and massive fundamental improvements to margins and cash flow. AppLovin has reported four consecutive quarters with revenue growth above 30% YoY, a major acceleration from late 2022 and late 2023 where three of four quarters saw declining revenues. Management expressed confidence in maintaining 20% to 30% YoY growth for the foreseeable future due to the efficiencies of AXON’s self-learning and catalysts from web-based e-commerce expansion.
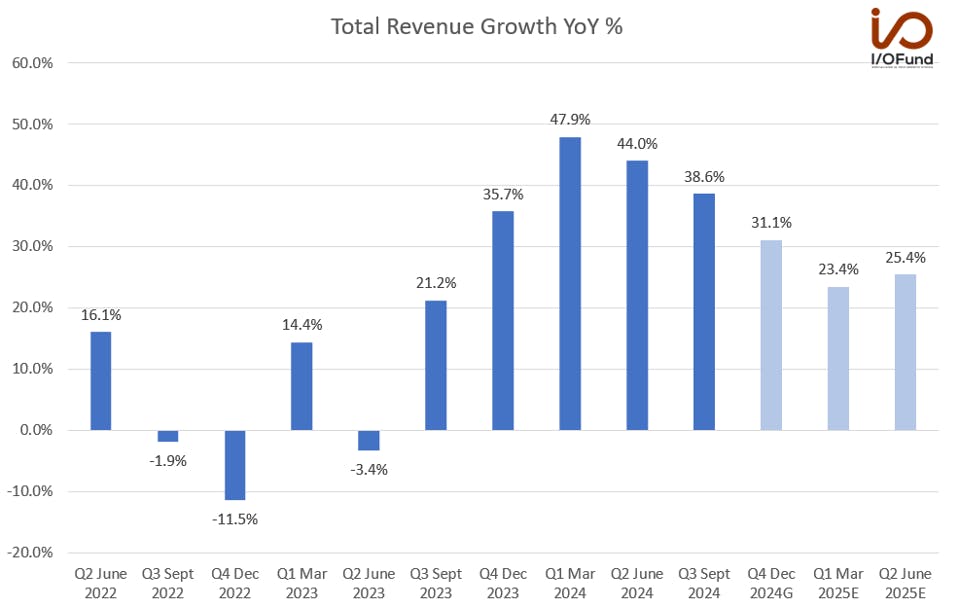
AppLovin has reported four consecutive quarters with revenue growth above 30% YoY, a major acceleration from late 2022 and late 2023. Source: I/O Fund
Not only has revenue accelerated substantially, but AppLovin’s margins have more than doubled further down the income statement. GAAP gross margin expanded more than 8 points to 77.5% in Q3, while operating margin rose more than 13 points to 44.6%. Taking a look annually, AppLovin is on track to potentially double its operating margin to ~38% from 19.7% in FY23. Additionally, net margin nearly tripled to 36% in Q3 on a GAAP basis, up from 13% a year ago. EPS rose 317% YoY to $1.25, with YTD EPS reaching $2.81, up 462% YoY.
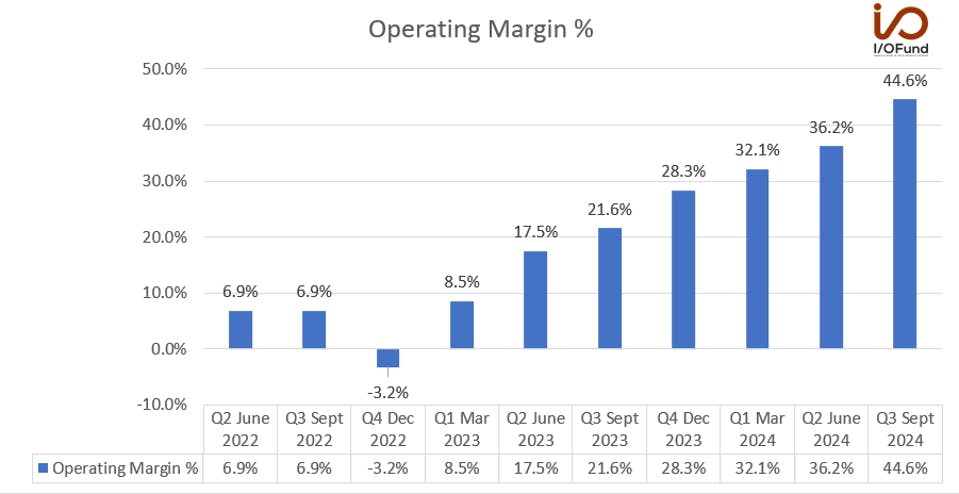
AppLovin is on track to potentially double its operating margin to ~38% from 19.7% in FY23. Source: I/O Fund
AppLovin’s near-flawless execution has also translated to strong cash flow generation, with operating cash flow margin doubling, rising from 23% a year ago to 46% in Q3. Free cash flow margin followed, reaching 45.5%, up from 22% a year ago.
This kind of operating leverage while maintaining revenue growth rates in the 30% range is quite rare indeed, separating AppLovin from a majority of its ad-tech and software peers. Analysts are excited to see what the company’s expansion to e-commerce can contribute to growth and a path to $6+ in EPS next year from AppLovin’s very strong margin profile.
Sign up for I/O Fund's free newsletter with gains of up to 2600% because of Nvidia's epic run - Click hereClick hereClick here
Palantir (PLTR)
Palantir joins this Top 5 list for a second-year running, with shares rising 356%. My firm’s free stock newsletter previously pointed out that Palantir was “one of the rare few that sees AI drive both real returns for its business and real value for its customers,” as it continues to crush its software competitors in AI-related growth. Palantir’s Artificial Intelligence Platform (AIP) has driven a significant revenue re-acceleration following its launch, with profitability also expanding – a rare combination for growth software stocks.
Palantir has capitalized on the AI software opportunity at hand via AIP’s unique value proposition, its scalability and versatility. November and December’s partnership announcements alone help demonstrate the versatility of Palantir’s platform, spanning numerous different industries from autonomous drone navigation to AI models for defense tech to more government program wins. Palantir benefits from the best of both worlds in both government contracts and AI exposure, as enterprise adoption of AI builds.
For a deeper look at AIP and how it has been transforming Palantir and driving revenue growth higher, read This Stock Is Crushing Salesforce, MongoDB And Snowflake In AI Revenue.This Stock Is Crushing Salesforce, MongoDB And Snowflake In AI Revenue.
Palantir’s 2024 was characterized by strong underlying AI momentum, with Q3 seeing revenue growth reach 30%, more than 10 points faster than when it entered the year and nearly 5 points above guidance for 25.2% growth. AIP has aided this revenue acceleration story by driving significant growth in Palantir’s US commercial segment, with the past two quarters seeing growth there above 50% YoY.
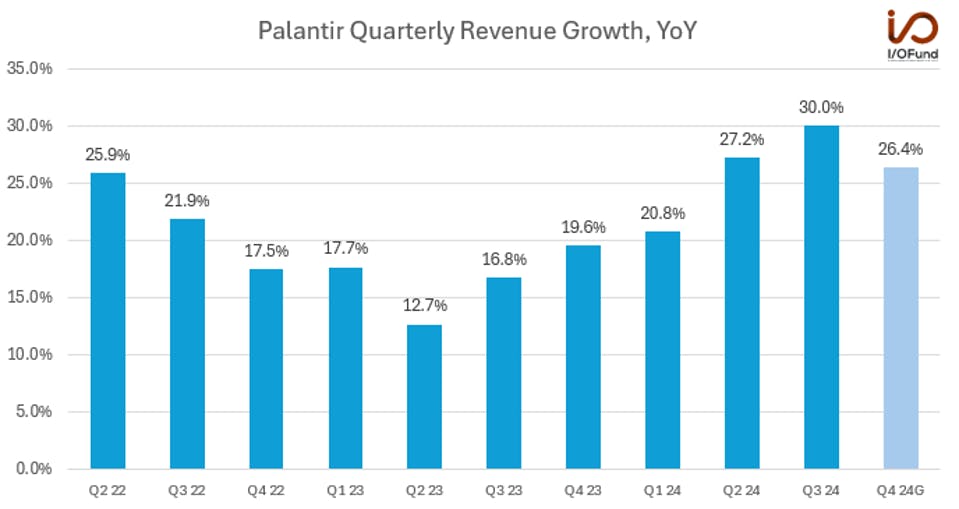
Palantir’s 2024 was characterized by strong underlying AI momentum, with Q3 seeing revenue growth reach 30%, more than 10 points faster than when it entered the year. Source: I/O Fund
Similar to AppLovin, these AI growth tailwinds are not just driving revenue, but also aiding operating margin expansion and EPS growth. GAAP operating margin was 16% for the second quarter in a row, up 9 points from last year, while adjusted operating margin is approaching 40% and has been >30% for four quarters in a row. Cash flow margins have been strong — operating cash flow was nearly $420 million, or a 58% margin, while adjusted free cash flow was $435 million, a 60% margin in Q3, up from the low-20% range in the first half of 2024. Palantir is targeting adjusted FCF of $1 billion-plus this year, or ~36% of revenue.
Fundamentally, to have revenue growth around 30%, free cash flow margin of 30%, and adjusted operating margin nearing 40% is impressive, to say the least. Palantir’s returns this year reflect that fundamental strength from AI-driven growth as well as optimism about its AI growth prospects for next year.
IonQ (IONQ)
Quantum computing stocks have been on a tear to end the year, with a handful of names seeing returns of more than 2,000% over the past three months. IonQ has risen 244% on surging enthusiasm for the quantum computing sector and revenue reaccelerating 40 percentage points over the past three quarters.
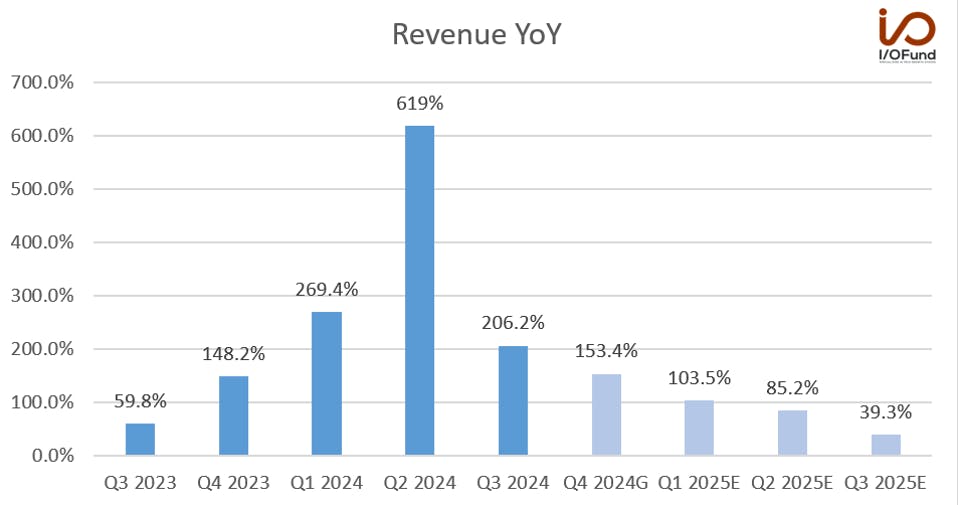
IonQ reported $12.4 million in revenue in Q3, with revenue growth of 102% YoY, following on 106% YoY growth in Q2. This has accelerated 42 points from 60% YoY growth in Q4, as IonQ is starting to quickly scale revenues as it has been consistently delivering on its technical roadmap ahead of schedule. IonQ also slightly raised its full year revenue guidance to $40.5 million at midpoint, for growth of 84% YoY.
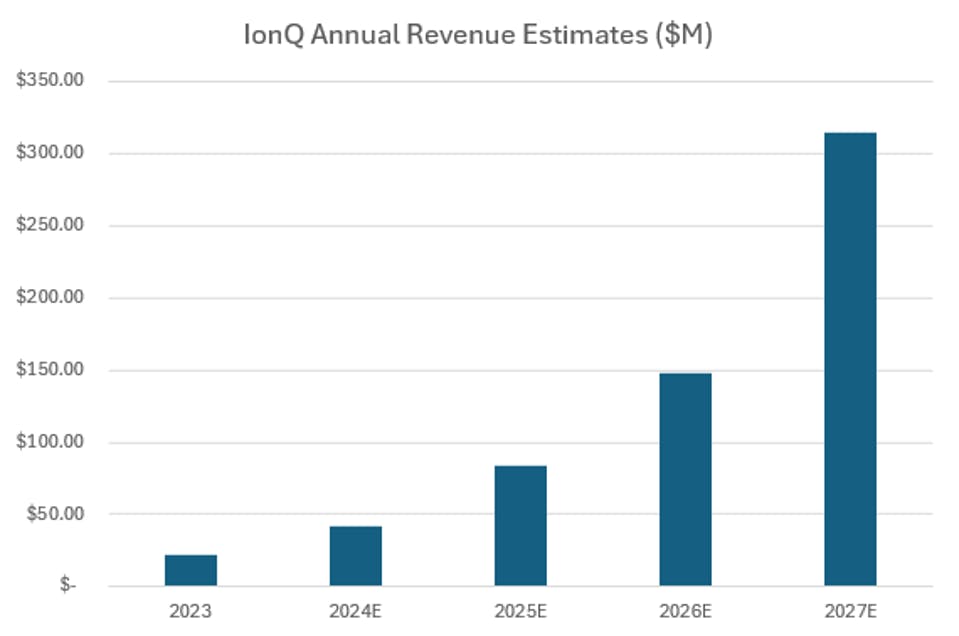
As it is still in its scaling phase, IonQ is by no means profitable or close to profitability, with analysts not expecting the quantum computing firm to break into profitability until well after 2027. However, revenue is currently expected to grow at a ~95% CAGR through 2027, from $22 million last year to an estimated $315 million.