
This article was originally published on Forbes on Nov 20, 2024,04:48am ESTForbesForbes on Nov 20, 2024,04:48am EST
Nvidia’s stock broke to all-time highs recently, trading at $148 in early November and $147 yesterday. The stock has left many investors wondering “what comes next” after the unrelenting, historic surge that began seven quarters ago.
To help my readers determine where Nvidia’s stock will go next, I’ve been fastidious in my analysis about the company’s outsized AI potential since 2018, tracking Big Tech capex as a proxy for AI demand since 2022, discussing the anomalous earnings and revenue revisions throughout 2023 and 2024, and reporting on never-before published data on supply chain checks as recent as two months ago.
The thoroughness is needed, however, as rumors from the media and short sellers alike run amuck. Rest assured, as 2025 approaches, supply chain data is giving bullish signals that the new generation of GPUs shipping in full volume by mid-2025 (and beginning to ship in the January quarter) will far exceed the GPU sales we saw in 2023 and 2024 combined.
Regarding my firm’s confidence in tracking supply chain data, when The Information stated Nvidia was experiencing a material delay on the next generation of GPUs, going so far as to state that Taiwan Semiconductor had machines sitting idle, I quickly refuted the report based on supply chain data my firm had been tracking. Those data points continue to indicate Blackwell is ramping. Here is what I stated:
“As of now, there’s a disconnect between next fiscal year’s revenue estimates of $167 billion and the $210 billion in GB200s alone expected to ship next year. Perhaps analysts are waiting for signals the supply chain can produce these outsized orders. So far, so good with the signals we see from TSMC and SMCI’s most recent earnings reports. Foxconn commentary helps, as well.”
Fast forward two months, and next year’s fiscal estimates stand at $185 billion up from $167 billion; showing no material impact from the delay (quite the opposite). Our firm was also able to use that same supply chain data to buy Nvidia in July/August, for an average cost basis of $109. The I/O Fund’s first trade was at $3.15, but we actively track the stock and publish our real-time trade alerts for anyone who feels they missed out on the AI juggernaut.
$5B+ in Blackwell Revenue for Q4
The first item that will determine the strength of the upcoming earnings report from Nvidia has nothing to do with the Q3 results. Rather, what the market will want to know is how much Blackwell revenue is expected in the January quarter. Morgan Stanley has estimates placed at $5 to $6 billion, with this number hitting a ceiling due to supply constraints; however, Piper Sandler sees Blackwell revenue potentially higher, at $5 billion up to $8 billion.
Given the company is lapping tough comparables, the growth rate will slow considerably even if Blackwell does ramp from $6 billion per quarter to $60 billion per quarter by late-2026 (Hopper is in its seventh quarter and Blackwell will be in its seventh quarter by late 2026). This is because excellence begets excellence, and thus, Nvidia is competing with itself with each new generation of GPUs. For example, with Hopper, the company reported peak quarterly growth of 262% and 265% earlier this year, yet is expected to slow to the mid-40% for growth as we close out 2025.
Nvidia has multiple levers it can pull and outside forces at play that will help it maintain this 40%+ growth rate. This includes a 1-year product road map, Big Tech’s large appetite for AI spending, and long-term AI GPU market growth from Enterprises and the Consumer, plus a commanding market share position.
By coming to market with upgraded, more powerful GPUs on a now-annual cadence, with Blackwell Ultra, Rubin and Rubin Ultra soon to come, Nvidia will continue to be the largest beneficiary of Big Tech’s AI capex to an unprecedented degree as the company continually raises the bar on performance and TCO upgrades with each new generation.
Additionally, Nvidia has a software moat with CUDA and the cash to reserve chip capacity in bulk at the fab level to maintain an 80% to 85% share of what executives foresee as a $500 billion AI accelerator market by 2028. I first covered these points in my free newsletter when I published: “Here’s Why Nvidia Stock Will Reach $10 Trillion Market Cap by 2030.”
Of these points, one of the most visible is that Nvidia continues to pry away tens of billions in cash – and now hundreds of billions —- from the world’s leading tech companies.
Big Tech Capex to Surpass a Quarter Trillion
All roads lead to Nvidia, and it’s no secret that Big Tech and others are competing to purchase Nvidia’s supply constrained GPUs. Our firm began tracking Big Tech capex as a proxy for Nvidia demand in 2022, and tracking it on a quarterly basis starting in early 2023 – to help gauge AI demand, I continue to track Big Tech capex quarterly closely for our readers.
Our recent checks published in the analysis “AI Spending to Exceed a Quarter Trillion Next Year” reveal that AI spending continues to accelerate, with Alphabet, Amazon, Microsoft, and Meta on track to increase their spend by ~$90 billion YoY in 2024. This does not include xAI, CoreWeave, Oracle and dozens of others who are also spending multiple billions on Nvidia’s GPUs, as well.
To better understand the trajectory of AI spending, let’s take a step back to 2023, where the rapid ascent of ChatGPT at the beginning of the year set the stage for AI to step into the spotlight.
- In the first half of 2023, Big Tech spent ~$74 billion on capex. Through Q3, that sum had moved up to ~$109 billion.
- In the first half of 2024, Big Tech spent nearly $104 billion, a 47% YoY increase. Through Q3, that sum had surged to $170 billion, up 56% YoY.
Big Tech could spend another $70 billion in Q4, based on guidance and comments from executives, who overwhelmingly discussed the need for more AI infrastructure, putting full year capex at ~$240 billion, or nearly 15% higher than the level they were tracking at the start of the year.
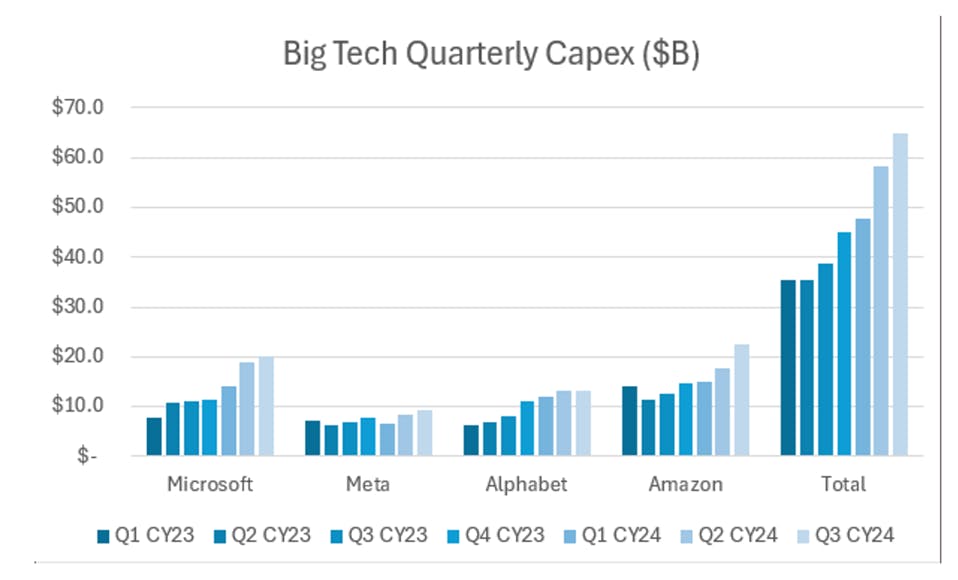
Big Tech’s Q4 capex could hit $70B, driven by AI infrastructure demand—pushing 2024’s total to ~$240B, up 15% from early-year estimates! Source: I/O Fund
For 2025, Big Tech has already signaled a willingness to spend substantially more on AI. There is clear ROI for Amazon, Google and Microsoft as they rush to meet the elevated demand that continues to outpace AI capacity in their cloud infrastructures. More broadly, Big Tech and large enterprises are racing to further develop and broaden AI services and models. UBS projects Big Tech will spend ~10% more YoY, placing AI-driven capex at $267 billion; however, if 2024 is any sign, this estimate is too low. This all fits in with longer-term projections from Bank of America that sees a cumulative $700 billion spent on AI through 2026.
Sign up for I/O Fund's free newsletter with gains of up to 2600% because of Nvidia's epic run - Click hereClick hereClick here
Nvidia Has Over 2X Better Margins Compared to Most Mag 7 Stocks
As we go through a lull between the Hopper generation being in its seventh quarter, and Blackwell not yet shipping in volume, our firm will be buying the dips on Nvidia for many reasons – one of them being it’s the market leader on margins. By having a near monopoly on GPUs, Nvidia has incredibly strong pricing power.
The GPUs coming in 2025, called Blackwell, are set to intensify this pricing power with DGX B200 systems reportedly going for up to a 40%+ premium to the previous DGX H100 systems, at $500,000 per server versus the low $300,000s per server, respectively.
While GB200 prices are estimated at $60,000 to $70,000 for a single chip, the NVL36 and NVL72 configurations carry much higher price tags and thus, higher average prices per GB200. For example, the NVL36 is expected to cost ~$1.8 million, and for 18 GB200s (36 B200 GPUs), that comes out to $100,000 per GB200 and additional components. For the NVL72, it works out to ~$83,333 per GB200 and additional components.
While there were concerns about Nvidia’s margins given that management guided for a sequential contraction in gross margins in Q3, the sheer pricing power of Blackwell will ultimately be a non-issue next year.
Nvidia’s operating margin of 62% exceeds second place Microsoft by 17.5 points and third place Meta by 21.9 points; Nvidia is more than double the rest of the Mag 7 including Apple and Alphabet. This is because Hopper’s pricing power versus the Ampere generation: Nvidia’s Compute and Networking operating margin expanded from 28.5% in Q3 FY23 when Hopper reached full production to 71.3% in the most recent quarter even as revenue grew 7x during that seven-quarter period.
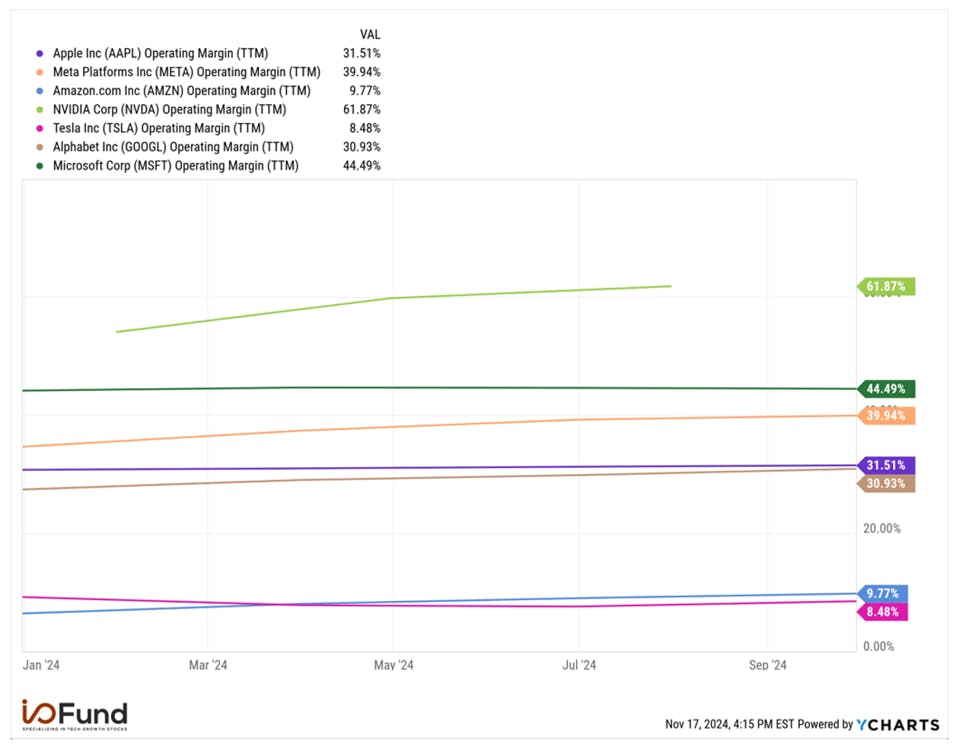
Nvidia leads the MAG 7 with a 62% operating margin, driven by Hopper’s pricing power—more than double Apple, Alphabet, and others in the group! Source: YCharts
Nvidia is expected to report roughly 50 bps to 100 bps margin contraction this quarter compared to last quarter, and will see roughly 200 bps to 300 bps margin contraction from its peak growth quarters earlier this year. As stated, the pricing power I foresee from Blackwell will keep the margins strong well into 2025, therefore, any concerns over margins this quarter will be a moot point by next year.
The strong margins combined with the expected growth in AI accelerators has caused some analysts to increase earnings per share substantially as of late. Bank of America increased its EPS estimates for next calendar year from $3.90 to $4.47 and for calendar year 2026 from $4.72 to $5.67.
In February, I wrote an analysis describing how Nvidia’s valuation was “eerily low despite 420% rally since 2023” to help our readers prepare for a higher return in the coming months, which detailed the importance of these revisions.
Ultimately, these revisions make the stock cheaper as it leads to more room in the bottom-line valuation. Despite being fairly straight forward, the velocity of the revisions is the single most important point that short sellers and Nvidia critics cannot seem to understand.