
The world today was engineered to be ephemeral and noisy. This is a terrible combination for an investor.
On Twitter alone, there are 456,000 messages sent every minute. On Facebook, there are 510,000 comments posted every minute and 293,000 status updates. Outside of social media, there are 16 million text messages sent every minute and 156 million emails.
For an investor, the antidote to noise is quality stock analysis. Due diligence requires dozens of hours per equity, and it takes hundreds of hours every year to produce a free newsletter with quality analysis. I/O Fund strives to offer some of the team’s best analysis for free, and we believe the consistency and depth of what we provide for free is hard to replicate.
We offer this in the most challenging sector for investors, which is hands-down the tech sector. The tech sector is unusually challenging because it involves many different verticals – artificial intelligence, crypto, consumer, media, cloud, and more. It’s also the highest risk and highest reward sector in the market. Due to sudden price movements in both directions, the stakes are high. Perhaps we are biased, but quality analysis particularly in the tech sector can be hard to come by.
Below are highlights from our free newsletter during a strong year for AI and crypto. Although numerous investor favorites rose more than 100% during the year, many other popular tech stocks declined significantly. We offered our readers clues and insights for the leading stocks in AI semiconductors and software, providing unparalleled depth and quality to our free readers.
Nvidia to Surpass Apple’s Valuation
Right out the gate in 2024, the I/O Fund’s free newsletter expanded on Lead Tech Analyst Beth Kindig’s highly regarded 2021 prediction that Nvidia would surpass Apple’s valuation within 5 five years; which at the time, this prediction was inconceivable as it would require not only Nvidia to go up more than 300%, but also for the tech leader Apple to plateau.
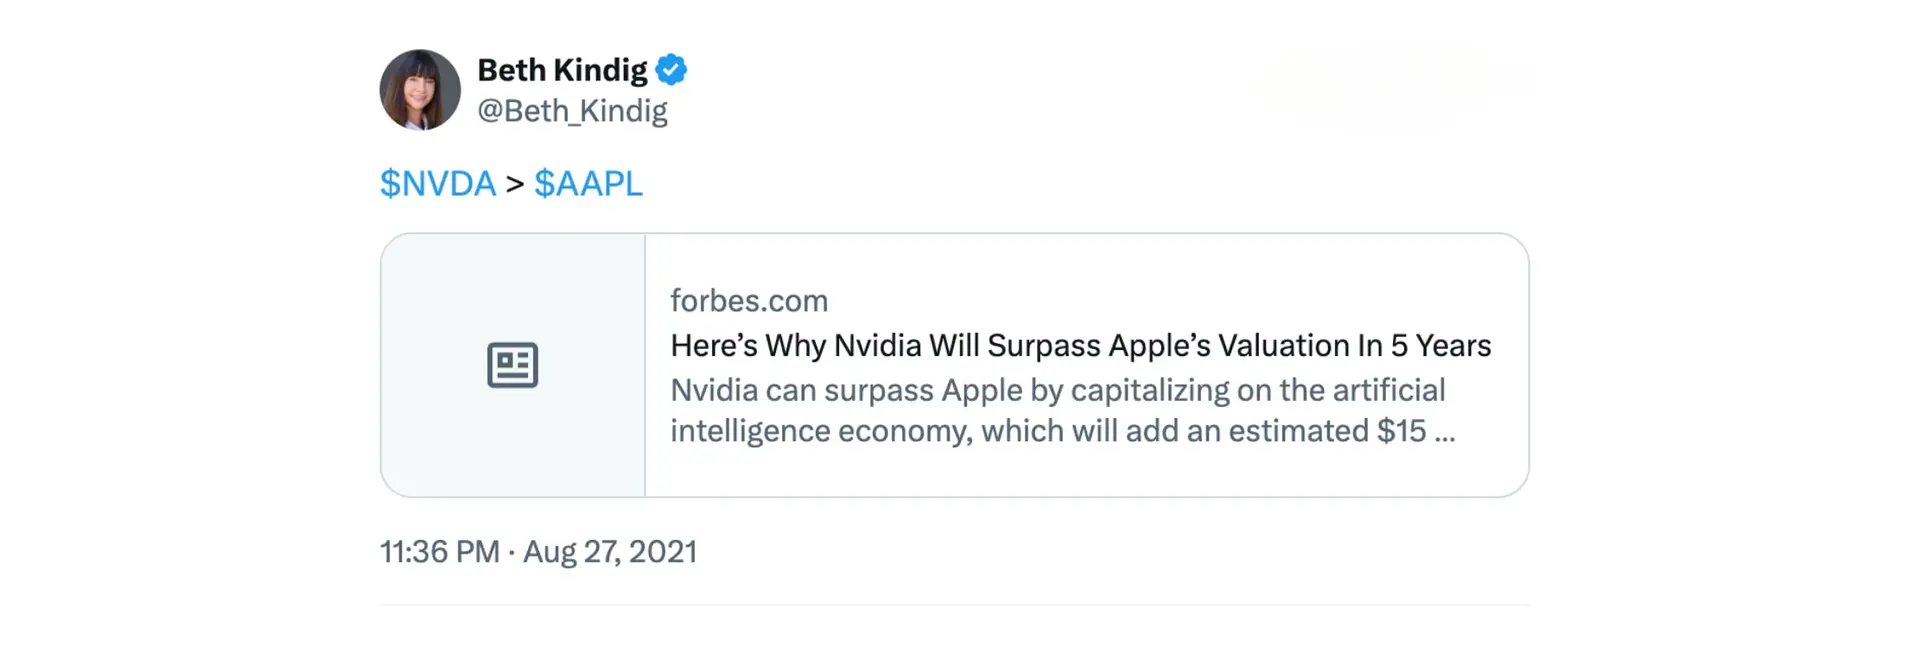
Kindig explained why she would deliver on this prediction a whole 2 years early in the February 2024 analysis, Nvidia Stock Gained $1.5 Trillion To Surpass The FAANGs – Apple Is Next. In the analysis, she pointed out that it was not just the consistency and magnitude of Nvidia’s multi-billion dollar revenue beats, but the expansion of its margins and earnings as revenue grew >200% for multiple quarters as it approached a $90 billion annualized scale.
From Kindig’s August 2021 prediction to the February 2024 update, Nvidia posted some staggering growth numbers:
- Data center revenue grew 676% to $18.4 billion. Data center revenue scaled from a $10 billion run rate to a $75 billion run rate in 2.5 years, a feat that took AWS 6 years to accomplish.
- Nvidia’s total revenue increased 240% during the period driven by blazing data center growth, versus a 43% increase for Apple, with iPhone revenue rising just 4.5% from fiscal 2021 to fiscal 2023.
- Nvidia’s quarterly EPS grew nearly 400% during the period, versus just 14% for Apple.
- Nvidia’s operating margin increased from 47% to nearly 67%, while Apple’s expanded from 28% to 34%.
The I/O Fund provided a handful of reasons that would propel Nvidia to quickly become the world’s most valuable company. This included the long runway for AI accelerators – AMD’s executives forecast the market to reach $400 billion by 2027 – with Nvidia taking the lion’s share. Nvidia’s accelerated product roadmap to a one-year release cadence lets it continue to pry away Big Tech capex, while the software opportunity beckons, already reaching a $1B+ run rate. These tailwinds combined with a valuation that was “eerily low” at the time considering the rapid ascent shares had made through 2023.
Supply chain and demand signals point to 2025 being another strong year for Nvidia as Blackwell comes to market, with the I/O Fund tracking these data points to assess Nvidia’s growth potential in the year to come. The I/O Fund has published numerous free analyses on Nvidia’s Blackwell; some of this explaining back in May why there was still room in the stock price as Kindig called out institutional analyst estimates being too low (which later materialized). Kindig also boldly wrote that delays on Blackwell were overblown, and we have gotten yet another confirmation from Nvidia’s management team at CES that Blackwell is shipping on time. The I/O Fund’s ongoing consistency and accuracy on this stock dating back to 2018 for up to 4,000% returns has been unparalleled –premium members received nine real-time buy alerts below $20 in 2021 and 2022; learn more here.
- Nvidia Q1 Earnings Preview: Blackwell And The $200B Data Center
- Nvidia Stock: Blackwell Suppliers Shrug Off Delay Ahead Of Q2 Earnings
- Here’s Why Nvidia Stock Will Reach $10 Trillion Market Cap By 2030
- Nvidia Stock Is A Buy On Dips Before Blackwell Arrives In 2025
- Nvidia’s Stock Has 70% Potential Upside For 2025
Bitcoin to $100K+
Portfolio Manager Knox Ridley provided two crucial updates on the I/O Fund’s game plan for Bitcoin, with his first update from April 2024 increasing the Fund’s target zones. At the time, Bitcoin was an overlooked asset compared to the over-hyped Mag 7, yet the asset has delivered superior returns compared to all of the great large-cap tech stocks in this bull cycle, minus Nvidia, while having a low inverse correlation to tech.
Utilizing technical analysis and on-chain data In the analysis We Are Raising Our Bitcoin Targets To $106K – $190K, Ridley explained that the I/O Fund was now raising its target zones for Bitcoin to $106,000 to $190,000, up from the previous zone of $75,000 to $130,000. Bitcoin was trading in the mid-$60,000 range at the time, with Ridley saying that “the $42,750 support region holds on any ongoing volatility, then we have no reason to doubt the uptrend in place.”
Ridley provided another update to the Bitcoin thesis at the end of July 2024 in the analysis, Bitcoin Update: Next Stop $100,000; Bitcoin finally surpassed that historic level as 2024 came to a close. He explained that Bitcoin had “a full corrective pattern in place that ended around $54,000 in early July,” which “suggests we are in the early stages of the next rally.”
The I/O Fund had systematically been accumulating since the start of this cycle while raising our critical supports along the way — below is the history of Bitcoin buy alerts that the I/O Fund issued to our subscribers in real-time since early 2023.
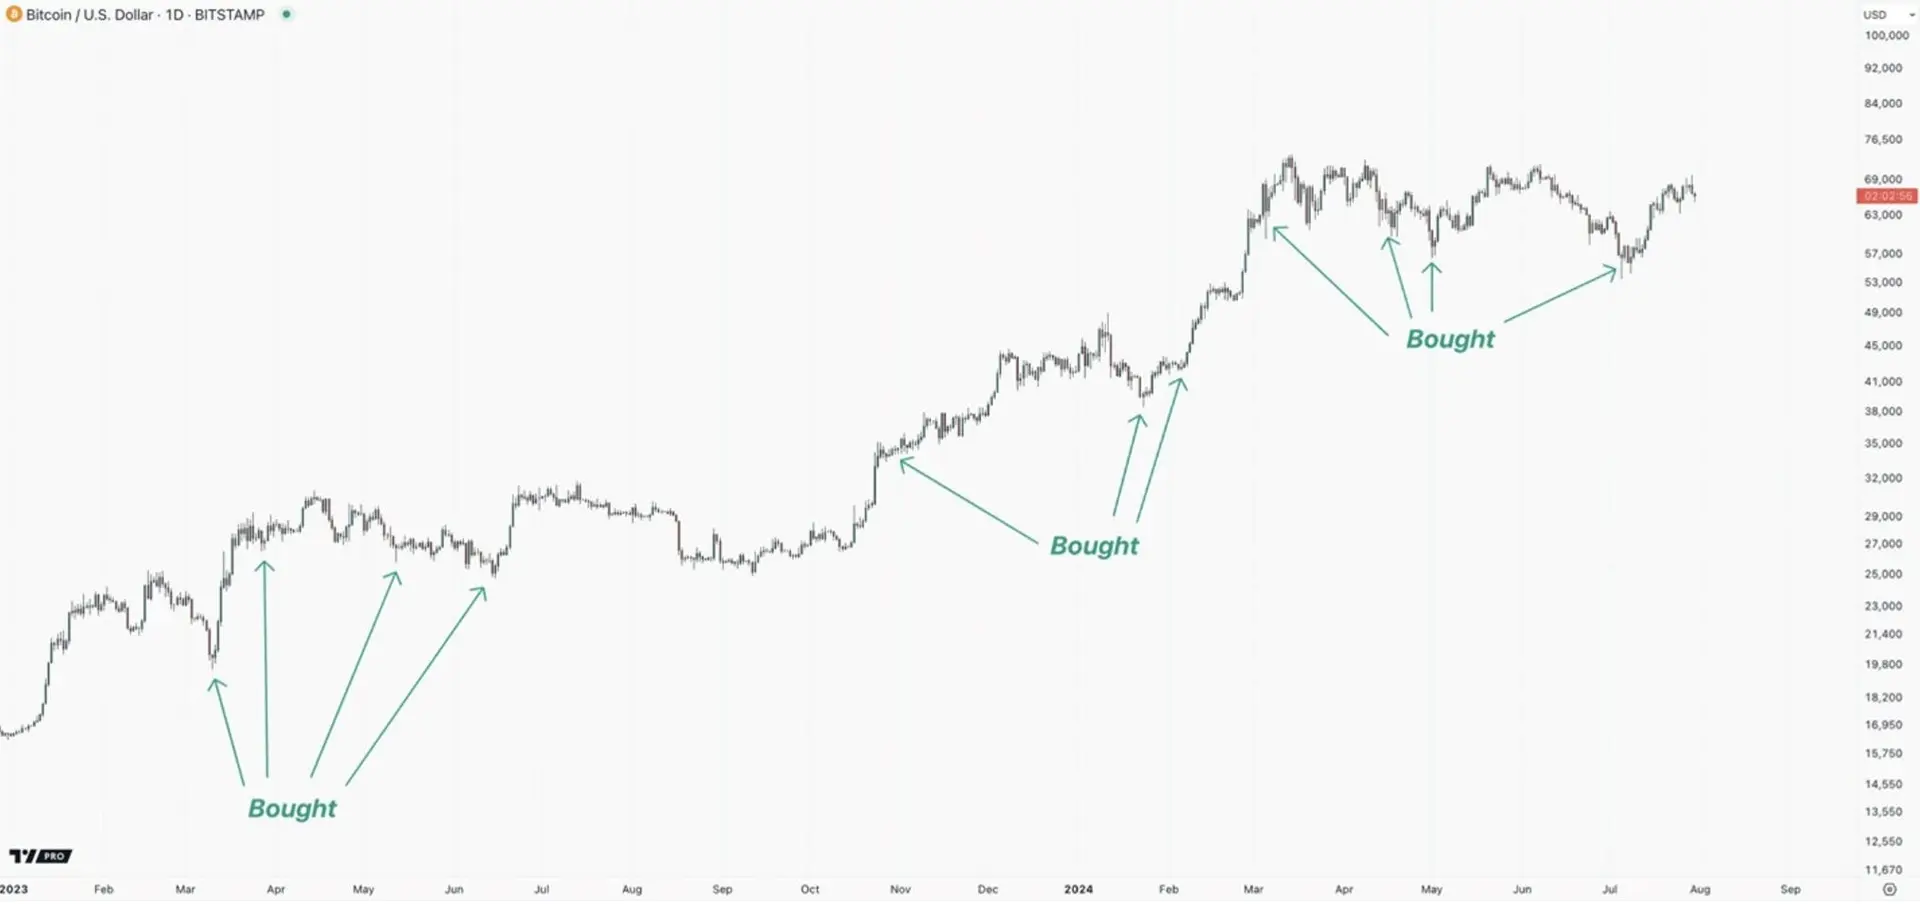
Notably, our firm assisted our readers in capturing immense upside from the two top-performing large-cap tech positions in 2023 and 2024 with Nvidia and Bitcoin; the fact we also provided ongoing entries and risk management for these mega-winners should not be understated in terms of the value we have delivered. To refer our newsletter to your friends and family, please click here.
Meta to Outperform Snapchat
In the January 2024 analysis, Social Media Stocks: One Metric Shows Meta’s Clear Leadership, the I/O Fund pointed out what separated Meta as a clear social media leader and why Snapchat would struggle with monetization. Since then, Meta shares have risen nearly 65%, while Snapchat has declined -28%.
Meta was demonstrating improvements in ad pricing with strong ad impressions growth of >30% in Q2 and Q3 2023, while average revenue per user (ARPU) accelerated in those quarters; whereas Snapchat was struggling to effectively monetize its user base. Additionally, we explained that Meta was much more efficient with spending, maintaining R&D spending below 40% of gross profit while improving ARPU, significantly improving operating margin, and investing in AR/VR and AI technologies. Snapchat was “spending around 80% of its gross profit dollars on R&D,” a disproportionately high amount on R&D relative to peers while failing to increase ARPU and monetization within its user base.”



